Are you unknowingly paying 25%+ APR to pay your insurance monthly?
Many businesses don't realise that spreading a premium into instalments comes at a steep hidden cost.
We fund monthly payments ourselves — at no extra cost to you.
Premium Funding APR Calculator
Important Information:
This calculator provides indicative estimates only and is intended for general information purposes. Premium funders may calculate and disclose APR using different methodologies and may exclude application fees, administration fees and other charges from their disclosed APR calculations. Actual costs may vary depending on policy inception date, loan commencement date, settlement timing, payment schedules and other factors. The "Funder Declared APR (excludes fees)" is intended to broadly reflect commonly disclosed premium funding APR calculations. The "Actual APR (including fees)" includes the application fee entered and may provide a better indication of the true cost borne by the customer. Results should not be relied upon as financial, legal, taxation or credit advice.
Most people don’t realise that spreading an insurance premium into monthly instalments often comes at a significant cost — and the way that cost is presented can make it look a lot smaller than it actually is. Whilst it doesn’t initially look like much, that is a huge cost and with very little risk (if you default the loan is secured by your insurance policies and is cancelled and a pro-rata refund issued).
What could you do with that extra saving? Broader covers that you ignored due to cost? A saving you could put towards a holiday? Or extra staff so you could spend more time with the family?
How premium funding works
When you pay monthly, your insurer or a premium funder is effectively lending you the money to pay your annual premium upfront, then collecting it back from you in instalments. For that service, they charge a flat fee on top of your premium — typically around 10%, though we do see rates ranging from 5% (usually on large premiums of $250,000+) up to 20%.
Using a $5,000 premium as an example:
- The funder adds 10%, so you owe $5,500
- They also charge an application fee — typically $50 to $100
- Before they’ve paid a single cent of your premium, they deduct your first instalment and their fee upfront
- Over the next 9 months, you repay the remaining balance
Why the real rate is much higher than it looks
With most loans — home loans, car loans, credit cards — interest is calculated on the outstanding balance. As you repay, the balance reduces, and so does the interest. Flat rate funding doesn’t work that way. The fee is charged upfront on the full amount, regardless of how quickly you repay.
In the example above, they collect $500 in interest (plus $50-$100 fees) to lend you $4,500 for 9 months. That’s where it starts to get interesting. APR (Annual Percentage Rate) is the standardised measure that Australian banking regulations require lenders to display, precisely so consumers can make fair comparisons. It accounts for the nominal interest rate plus fees, and reflects the true cost of a loan based on the actual balance outstanding at each point in time.
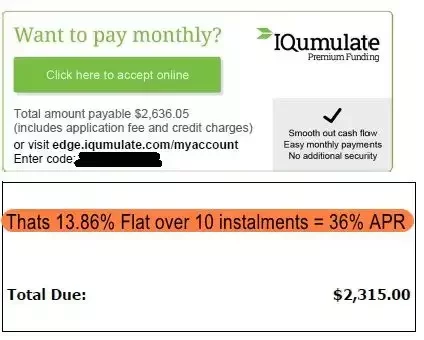
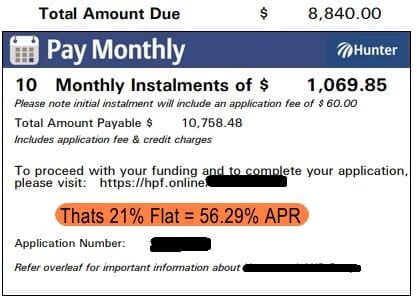
When you apply the APR calculation to a typical 10% flat rate premium funding arrangement, the equivalent APR is 26.21%. We’ve seen some funders charge flat rates as high as 21.7% — which translates to an APR of over 55%.
Some funders have signed up to the new AFIA Premium Funding Code of Practice, which now requires them to show you the APR on your contract. The funders currently compliant with this code include Arteva Funding, Attvest, Clearmatch, Elantis, Hunter Premium Funding, IQumulate and Oz Premium Finance. If your funder isn’t on that list, your contract may not show you the APR at all.
You can read the Code of Practice here. However that APR calculation excludes any fees charged and does not take into account things like:
- What date did the loan start (if after the start of the policy, the loan period shortens, which means the APR would increase)
- When are they paying the premium to your broker (some are as quick as overnight, but most are around 7-30 days, again this would increase the APR)
This is all explained in the contract, however you might struggle to find it in the 4 page fine print and our calculator doesn’t include those factors, as you wouldn’t know how long a funder takes to pay the broker (its not disclosed on your contract).
We are not trying to ‘bash’ premium funders. They provide a valuable service, making insurance covers affordable and manageable for business owners that may otherwise struggle to pay their annual premiums and potentially under insure etc, but we are insurance brokers, not financiers. We don’t believe that insurance brokers need to be paid more, just because you want to pay monthly (commissions paid by the funders to the broker range from 0-5% FLAT, but are generally around 2%) and we want to see monthly options being made more affordable.
So how does OBIB offer monthly payments at no extra cost?
A few reasons — and we think it’s worth being transparent about this. First, some insurers allow policies placed via an insurance broker to be paid monthly directly with them at no additional charge. It’s simply the annual premium divided by 12. We wish they all worked this way. However, not all insurance brokers pass this on. You’d have to ask them why, but in most cases, they receive a commission from Premium Funders (disclosed on most contracts) and they don’t like receiving commission from insurers ‘on the drip’ each month.
For insurers that don’t offer this, we fund the premiums ourselves on behalf of our clients. As we fund millions of dollars in insurance premiums each year, we’ve negotiated a very low funding rate — one we absorb rather than pass on to you. We believe cost shouldn’t be a barrier to getting the cover you need.
Does this mean we earn a little less than some brokers? Yes. But with a mix of clients who prefer to pay annually, and those we can fund directly through insurers at no cost, the overall impact is manageable — and we think offering genuinely fee-free monthly payments is a fairer outcome for our clients and a point of difference worth having.
Ready to see what OBIB can do for you?
I have an existing policy that I want to pay monthly with no extra costs
Had enough of 25%+ rates and just want to pay your existing policy monthly, with no extra costs? This link will take you to our "Transfer" option. You can Upload your current notice and complete an authority for OBIB to take over your current policy instantly. In 60 seconds you wont be paying any more to pay monthly (as a bonus we will also review the market for you).
Don't have policy or maybe don't
trust us yet?
This link will allow you to complete a form (or upload a schedule) and our qualified Australian Brokers will review your cover, come back to you within one business day with tailored advice and options from at least 10 insurers - all with free monthly payments available.
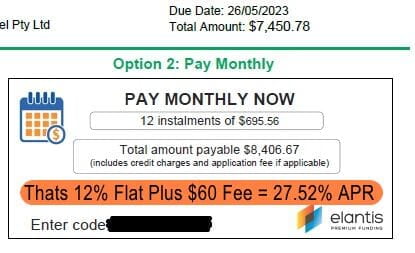
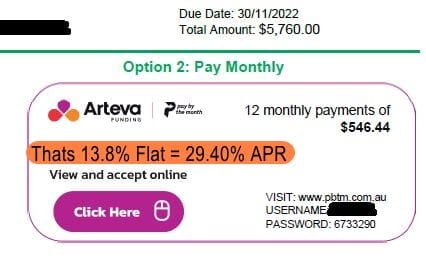
Real rates from real client notices
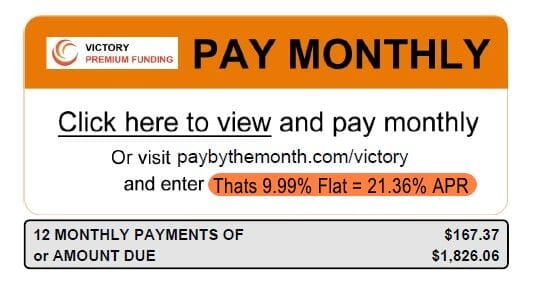
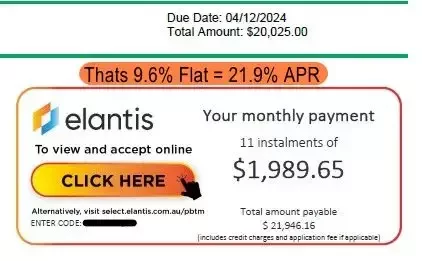
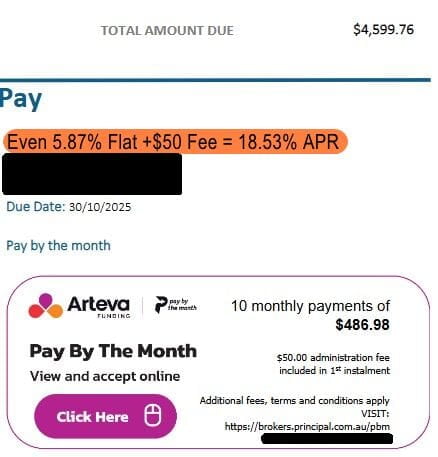
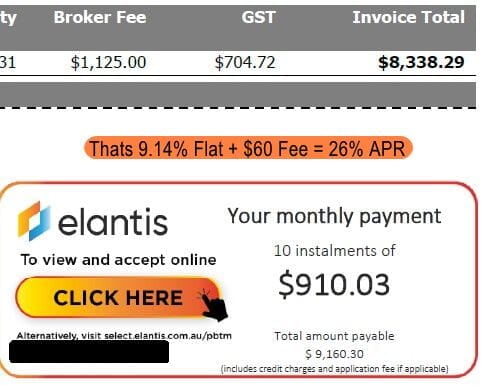
Here are some extracts from notices our clients have provided. The orange overlay shows the real rates.
Terms & Conditions:
1. Not all insurers work with brokers, we refer to these as “Direct Insurers”. Most have an affiliated company that deals with brokers that we can deal with, but if your policy is with a Direct Insurer, we will not be able to take it over (most Direct Insurers don’t charge more for monthly, IF they offer it).
2. For us to be able to offer you free monthly, the policy can’t be past the renewal date. But don’t let that put you off, still upload it and the team will still go to work and come back to you with options from at least 10 insurers with tailored advice for your business and in most cases we do have more competitive options that we can discuss with you.